Insurer reverses a storm claim denial
The insurer called it flood damage. An engineer's report pointed to the wind.
The questionWhat happens when an insurer says storm damage was flooding and not wind?
Illustrative example
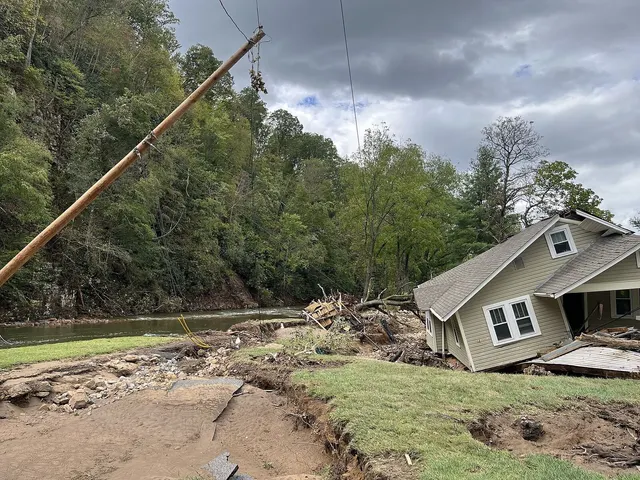
NEW ORLEANS, La. — An insurer has paid $312,000 to a homeowner after reversing its decision to deny a hurricane claim.
The company had said the damage came from flooding, which the policy did not cover. The family said the roof failed and rain poured in hours before any water rose in the street.
The answer would decide whether the family could rebuild. It also turned on a question that shapes many storm claims: who decides what caused the damage.
Faravel Law hired an independent engineer, who documented the roof failure and wind-driven rain damage on the upper floor, well above the flood line. The firm filed suit using that report.
The insurer withdrew its denial and paid $312,000 under the policy.
The payment covers wind damage only. The family's flood losses remain uninsured.
The stated cause of damage can decide coverage. Lawyers in storm-hit areas often advise getting an independent inspection before accepting a denial.
About this story
Submitted by the firm. Source review: supporting documents reviewed by result.law. See our publication standards.
Related stories
 Insurance
The Insurer Offered a Partial Roof Repair. How an Oklahoma Homeowner Challenged the Scope
 Insurance
Hail Damaged the Roof, but the Insurer Disputed Replacement. How a Kansas Owner Challenged the Decision
 Commercial
A Business Was Charged for Repairs It Disputed. How a Nevada Tenant Challenged the Bill
 Property
An HOA Ordered a Homeowner to Remove a Renovation. Here’s How the Dispute Was Resolved